SK Hynix Announces Q3 2026 Financial Results – A Boost for the Korean Stock Market!
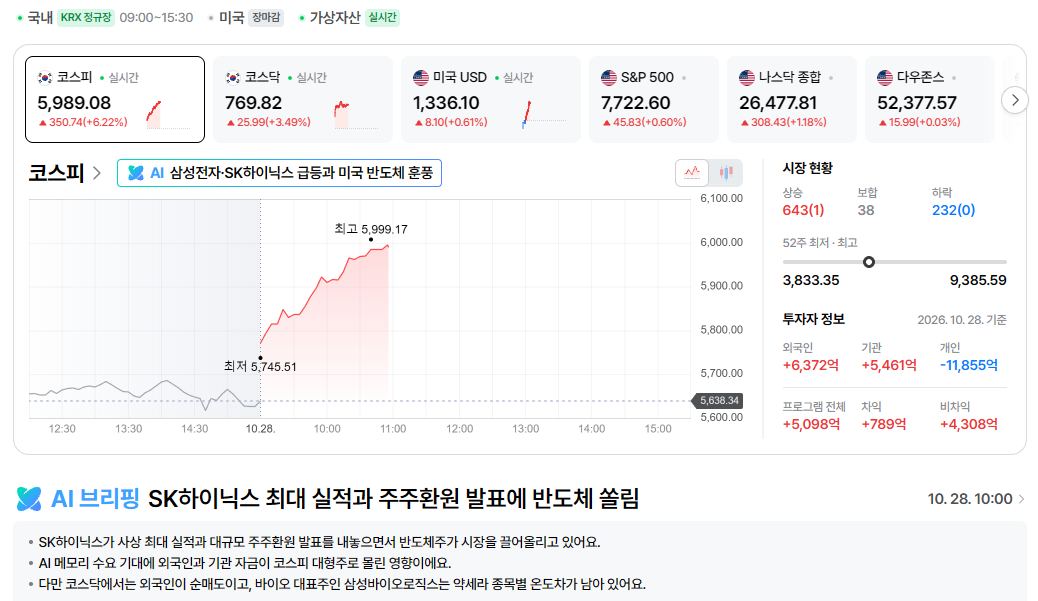


​

SK Hynix Announces Q3 2026 Financial Results

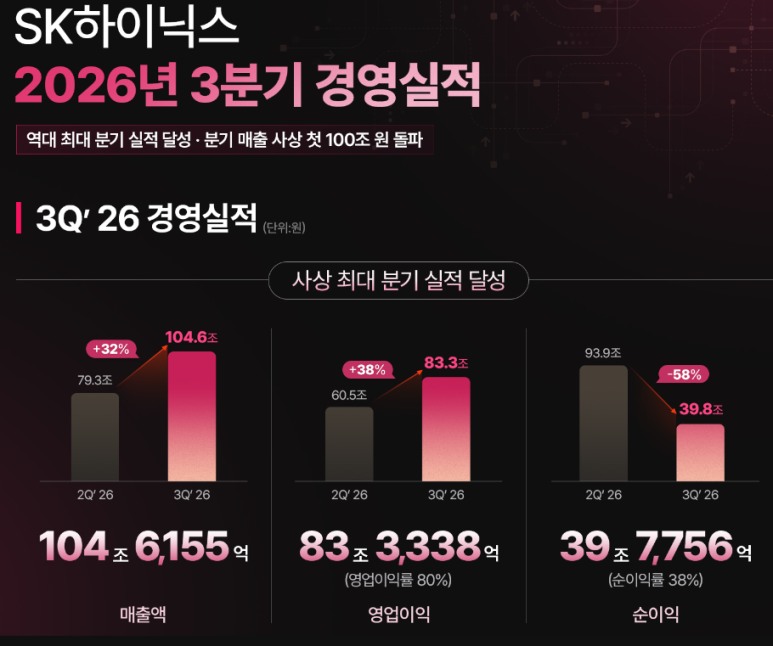
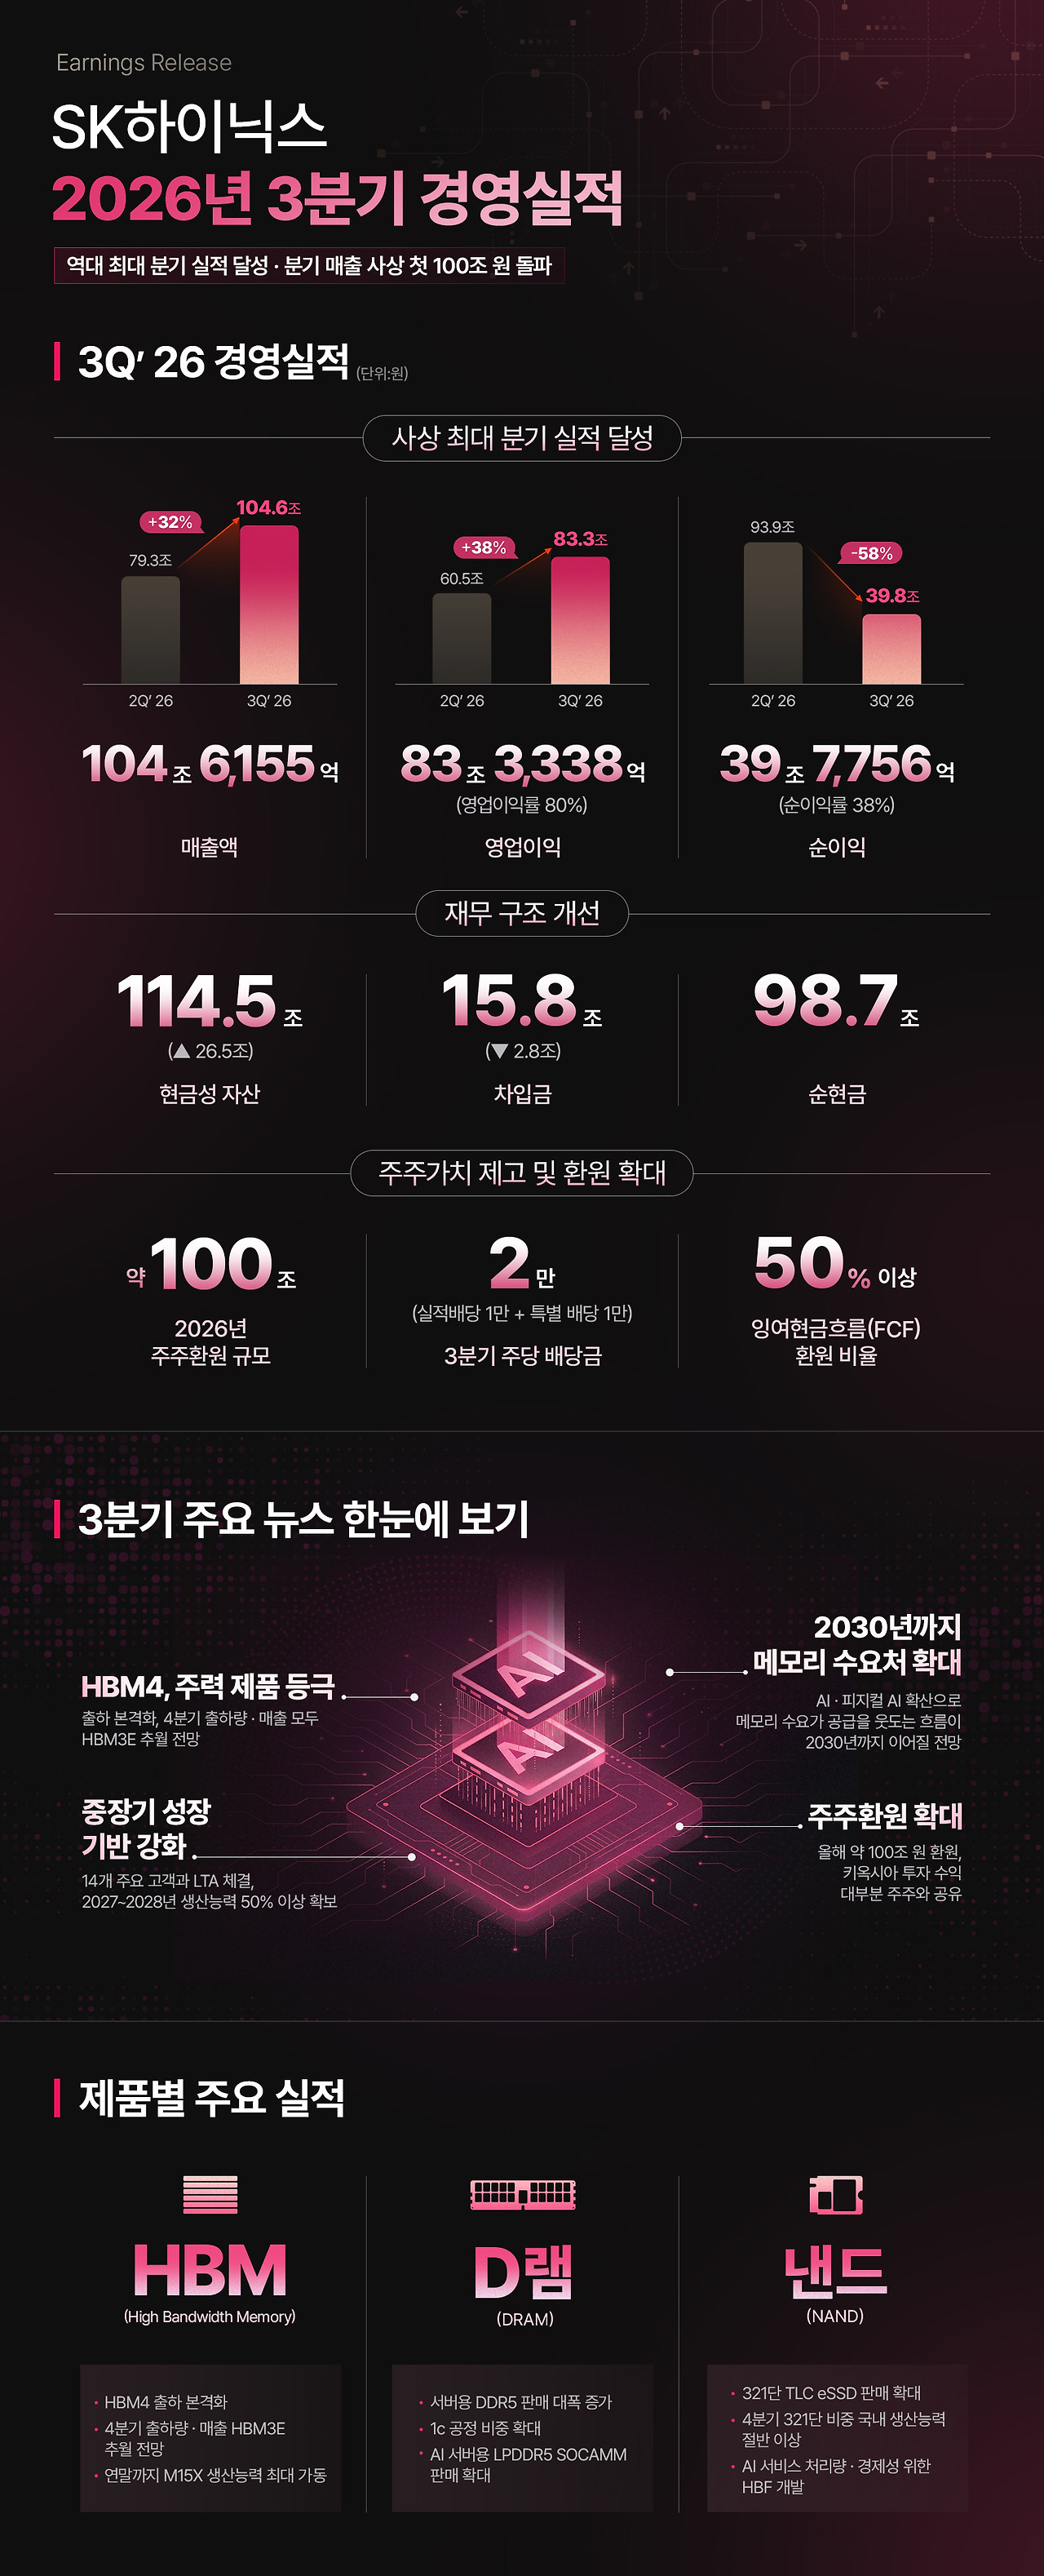
Revenue of KRW 104.6155 trillion, operating profit of KRW 83.3338 trillion, and net profit of KRW 39.7756 trillion—quarterly revenue surpasses the KRW 100 trillion mark for the first time in history.

Expanded sales of high-value-added products, including HBM4 and server-use memory; HBM4 set to become a flagship product starting in the fourth quarter.

Secured long-term supply contracts covering over 50% of production capacity for 2027–2028, ensuring stable profitability through a market-responsive pricing structure.

Approximately KRW 100 trillion in shareholder returns to be executed this year; the majority of gains from the Kioxia investment will be shared with shareholders.

On the 28th, SK Hynix announced its financial results for the third quarter of this year: revenue of KRW 104.6155 trillion, an operating profit of KRW 83.3338 trillion (an operating margin of 80%), and a net profit of KRW 39.7756 trillion (a net margin of 38%). (Based on K-IFRS)

​

​

Record-High Quarterly Revenue and Operating Profit—Revenue Surpasses KRW 100 Trillion for the First Time

Driven by rising prices for key products amid growing demand for AI memory, the company leveraged its competitive edge in high-value-added products to achieve record-high quarterly revenue and operating profit. Notably, revenue exceeded the KRW 100 trillion threshold for the first time in the company’s history. Both revenue and operating profit saw quarter-over-quarter increases of 32% and 38%, respectively. * Q2 2026: Revenue of KRW 79.3187 trillion, operating profit of KRW 60.5426 trillion

By product category, the ramp-up in HBM4 shipments, combined with a significant surge in sales of server-grade DDR5, drove growth in the DRAM segment. In the NAND segment, increased sales of 321-layer TLC eSSDs contributed to the continued growth of high-value-added products destined for data centers.

The company’s financial structure has also strengthened further. As of the end of the third quarter, cash and cash equivalents reached KRW 114.5 trillion—an increase of KRW 26.5 trillion from the previous quarter—while total borrowings decreased by KRW 2.8 trillion to KRW 15.8 trillion. Consequently, net cash rose to KRW 98.7 trillion.

Memory Supply Shortage Expected to Persist Through 2030

SK Hynix has observed the emergence of a virtuous cycle: the growing use of AI—across areas such as software development, customer service, and search—is boosting productivity and generating new revenue streams, which in turn drives further investment in infrastructure. Furthermore, the company noted that AI investment is moving beyond its initial phase, where it was concentrated among a few select firms, to encompass a broader range of enterprises and even national-level initiatives. As a result, the global market for AI data center infrastructure is expected to maintain steady growth.

The memory market is also projected to continue its upward trajectory, fueled in the short term by AI applications for enterprises and individuals, and in the medium to long term by "physical AI"—such as autonomous driving and robotics.

On the supply side, however, the company assessed that production capacity is failing to keep pace with market growth. Given the increasing technical complexity of advanced manufacturing processes and the long lead times required to construct new production facilities, it is anticipated that demand will continue to outstrip supply through 2030. Driving Further Growth Next Year Through Expanded Production Capacity and Enhanced Product Competitiveness

Leveraging these favorable conditions, the company plans to accelerate the expansion of its production capacity and strengthen its product competitiveness. By sustaining its current growth momentum, the company aims to reach a new level of revenue and profit in the coming year.

The strategy includes rapidly increasing the share of the 10nm-class 6th-generation (1c) process, while boosting sales of DDR5 and LPDDR5 LPCAMM products designed for AI servers—thereby further reinforcing a DRAM portfolio centered on high-value-added offerings.

To meet the surging demand for HBM, the company intends to maximize production capacity at its M15X facility by the end of the year, ramping up the output of HBM4. Consequently, the company expects HBM4 to surpass HBM3E in both shipment volume and revenue by the fourth quarter, establishing itself as the flagship product.

In the NAND sector, the company plans to increase the share of its core 321-layer process to account for more than half of its domestic production capacity by the fourth quarter, facilitating a rise in the supply of high-performance, high-capacity eSSD products. In the mid-to-long term, the company aims to position its NAND technology—supported by HBF (High-Bandwidth Flash) and system optimization—as a key solution for enhancing the throughput and cost-efficiency of AI services.

Securing Long-Term Supply Agreements for Over 50% of Production Capacity Through 2027–2028; Significant Investment Expansion Planned for Next Year

To improve visibility into mid-to-long-term demand and solidify its foundation for growth, SK hynix is ​​expanding its Long-Term Supply Agreements (LTAs) with customers. The company has currently entered into Long-Term Agreements (LTAs) with 14 major clients, including a global, large-scale Cloud Service Provider (CSP). It is also proactively discussing the potential extension of these contracts—which typically span five years—with some of these clients.

The volume secured through these LTAs accounts for more than 50% of the company’s total production capacity for 2027 and 2028. The company explained that it has established a structure that ensures stable profitability while allowing for flexible responses to market shifts, by incorporating a mechanism that adjusts pricing—within an agreed-upon range—to reflect prevailing market conditions.

Building on this clear demand visibility, the company is moving to expand its production capacity. With infrastructure investments ramping up both domestically and internationally—including the full-scale launch of the first fabrication plant (Fab 1) in Yongin next year—total investment spending is expected to increase significantly compared to this year. However, the company plans to remain flexible regarding the scale and timing of these investments, carefully evaluating factors such as client demand, product competitiveness, profitability, and investment efficiency.

Approximately 100 Trillion Won in Shareholder Returns This Year; Most Gains from Kioxia Investment to be Shared with Shareholders

As previously signaled in August, SK Hynix announced additional shareholder return measures today. The company plans to return approximately 100 trillion won to shareholders, comprising over 30 trillion won in cash dividends (based on the 2026 fiscal year) and more than 60 trillion won in share buybacks and cancellations—a figure that includes the 40 trillion won buyback program announced in August. This initiative fulfills the company’s commitment to return at least 50% of its Free Cash Flow (FCF) to shareholders. Notably, the 40 trillion won share buyback program announced in August was completed last week, and the shares are set to be cancelled shortly. The company announced a policy to determine dividend payouts based on operating performance, while also committing to provide additional returns through special dividends whenever significant investment gains are realized. Furthermore, the company pledged to continue share buybacks on a quarterly basis.

During the board meeting held today, it was resolved to distribute 14 trillion won in cash dividends for the third quarter and to execute 20 trillion won in share buybacks. Of the shares to be repurchased, 10 trillion won worth—intended for shareholder returns—will be entirely retired (cancelled). The remaining 10 trillion won is earmarked for employee compensation and is therefore excluded from the scope of shareholder returns.

The third-quarter dividend is set at 20,000 won per share, consisting of a 10,000-won dividend reflecting improved operating performance and a 10,000-won special dividend representing a share of the gains from the investment in Kioxia. The company has decided to return the vast majority of the profits realized from its Kioxia investment this year to its shareholders.

SK Hynix emphasized, "Moving forward, we will continue to deliver stable results, driven by robust growth in memory demand and our technological competitiveness, and we remain committed to consistently sharing these outcomes with our shareholders." 


■ Q3 2026 Financial Results Comparison Table (Based on K-IFRS)

(단위:억 원)
2026년 3분기
Q2’26
증감률
Q3’25
증감률
매출액
1,046,155
793,187
32%
244,489
328%
영업이익
833,338
605,426
38%
113,834
632%
영업이익률
80%
76%
3%p
47%
33%p
당기순이익
397,756
939,226
-58%
125,975
216%


※ Prepared in accordance with the Korean International Financial Reporting Standards (K-IFRS).

※ These financial results have been prepared prior to the completion of an accounting review by an external auditor and are subject to change during the review process.

※ Growth rates are calculated based on the original figures prior to rounding.


===============================================

​

[October 28, 2026]


SK Hynix Announces Q3 2026 Financial Results

Ø Revenue of KRW 104.6155 trillion, operating profit of KRW 83.3338 trillion, and net profit of KRW 39.7756 trillion… Quarterly revenue surpasses KRW 100 trillion for the first time in history

Ø Increased sales of high-value-added products, including HBM4 and solutions for servers… HBM4 to Emerge as a Key Product Starting in the Fourth Quarter

Ø Long-term supply agreements secured for over 50% of production capacity through 2027–2028; stable profitability ensured through structures that reflect market conditions.

Ø Approximately KRW 100 trillion in shareholder returns to be executed this year; the majority of gains from the Kioxia investment to be shared with shareholders.


SK Hynix announced on the 28th that it recorded KRW 104.6155 trillion in revenue, KRW 83.3338 trillion in operating profit (an 80% operating margin), and KRW 39.7756 trillion in net profit (a 38% net margin) for the third quarter of this year. (Based on K-IFRS)


■ Record-High Quarterly Revenue and Operating Profit; Revenue Surpasses KRW 100 Trillion for the First Time


Driven by rising prices for key products amid growing demand for AI memory, the company achieved record-high quarterly revenue and operating profit, bolstered by its competitiveness in high-value-added products. Notably, revenue exceeded KRW 100 trillion for the first time in the company’s history. Both revenue and operating profit increased by 32% and 38%, respectively, compared to the previous quarter.


* Q2 2026: Revenue of KRW 79.3187 trillion, Operating Profit of KRW 60.5426 trillion


By product category, the ramp-up of HBM4 shipments, combined with a significant surge in sales of server-grade DDR5, drove growth in the DRAM segment. In the NAND sector, the expansion of 321-layer TLC eSSD sales contributed to continued growth across high-value-added products destined for data centers.


The company’s financial structure has also become even more robust. At the end of the third quarter, cash and cash equivalents stood at 114.5 trillion won—an increase of 26.5 trillion won from the previous quarter—while borrowings decreased by 2.8 trillion won to 15.8 trillion won. Consequently, net cash expanded to 98.7 trillion won.


■ Memory Supply Shortage Expected to Persist Through 2030


SK Hynix has observed the emergence of a virtuous cycle: the growing use of AI—which enhances productivity and generates new revenue streams across diverse fields such as software development, customer service, and search—is driving an expansion in infrastructure investment. Furthermore, the company noted that the base of AI investment is broadening beyond a handful of firms to include a wider range of enterprises and even national-level initiatives, suggesting sustained growth for the global AI data center infrastructure market.


The memory market is also expected to maintain its growth trajectory, driven in the short term by AI applications for both enterprise and personal use, and in the medium to long term by "physical AI"—such as autonomous driving and robotics.


On the other hand, the company assessed that supply is failing to keep pace with the speed of market growth. This is due to the increasing technical complexity of advanced manufacturing processes, as well as...

Posted by 보석
,

U.S. Treasury Secretary’s Remarks Emphasize Need for Further Interest Rate Hike in Japan and Hint at Measures to Strengthen the Yen

Japanese Financial Institutions Fear Massive Selling of U.S. Treasury Bonds Held to Defend the Yen

**Scott Bessent, the U.S. Treasury Secretary,’s remarks emphasizing the need for further interest rate hikes in Japan and hinting at measures to strengthen the yen represent an acknowledgment of the realistic limitations that joint foreign exchange market intervention (selling dollars and buying yen) alone is insufficient to prevent the dollar/yen exchange rate from breaking the 160 yen mark. It signifies a strong call for the Bank of Japan (BOJ) to directly implement monetary tightening (interest rate hikes).

Breaking the traditional diplomatic taboo of respecting the independence of other central banks, the U.S. Treasury Secretary’s direct demand for an interest rate hike in Japan signifies that the burden placed on the U.S. and global financial markets by the extreme weakness of the yen has reached its limit. 1. Key Background of the Remarks

Limitations of Foreign Exchange Intervention: Despite direct market intervention by U.S. and Japanese authorities, the value of the yen has once again fallen below the 160 yen per dollar mark due to the significant interest rate differential between the two countries.

Protection of the U.S. Treasury Market: If the value of the Japanese yen continues to plummet, Japanese financial institutions will sell off large quantities of U.S. Treasury bonds they hold to defend the yen. This will forcibly drive up the yield on U.S. 10-year Treasury bonds, causing borrowing costs (interest burdens) for the U.S. government, corporations, and households to skyrocket.

U.S. Intention: Rather than a simple dollar-selling intervention (a stopgap measure), the U.S. demanded a structural solution requiring Japan to voluntarily raise its benchmark interest rate to normalize the value of the yen. 2. Analysis of the Impact of Japan's Interest Rate Hike on Various Countries

■ Benefits for the United States

Stabilization of U.S. Treasury yields (Easing of Treasury burden): If Japan raises interest rates and stabilizes the weak yen, the risk of Japanese institutions dumping U.S. Treasuries to defend the dollar decreases. This prevents upward pressure on the U.S. 10-year Treasury yield.

**Stabilization of import prices and alleviation of the trade deficit:** If the excessive strength of the dollar relative to the strong yen is alleviated, U.S. export competitiveness improves, and pressure regarding the trade deficit with Japan is reduced.

■ Benefits for Japan

Curing chronic ultra-weak yen and import inflation: As the value of the yen rises, import prices for raw materials, energy, and food stabilize, improving the real purchasing power and consumer sentiment of the Japanese people. Return to Normal Monetary Policy (Monetary Policy Normalization): This allows us to shake off the side effects (asset bubbles, currency depreciation) of the ultra-low interest rates of 'Abenomics' that have persisted for the past decade or so, and transition the economic structure to a normal interest rate system.

■ Benefits for Korea

Easing Upward Pressure on the Won/Dollar Exchange Rate: The Won tends to strongly correlate (couple) with the Japanese Yen in the foreign exchange market. When the value of the Yen rebounds, downward pressure on the Won is also alleviated, contributing to the stability of the Won/Dollar exchange rate and import prices.

Restoration of Price Competitiveness for Korean Export Companies: The price competitiveness of major domestic export items—such as automobiles, steel, and machinery—that compete with Japanese companies in the global market rises relatively due to the effect of the strong Yen.

Easing the Mobility for the Bank of Korea's Monetary Policy Operations: As factors of exchange rate instability diminish, it becomes much easier for the Bank of Korea to implement monetary policies tailored to domestic economic conditions. ■ Negative Aspects for Korea (Risk Factors)

**Increased Financial Market Volatility Due to Yen Carry Trade Unwinding:**

Funds (Yen Carry funds) that were borrowed in low-interest Yen and invested in high-yield assets, such as stocks and bonds in global emerging markets including Korea, may be withdrawn.

If Japanese interest rates rise sharply, there is a risk that the Korean stock market (KOSPI) and Asian financial markets may experience temporary shocks or sharp declines as foreign investors withdraw their funds.

**Increased Costs for Travel/Shopping in Japan (Personal Aspect):** Due to the appreciation of the Yen, the financial burden of local accommodation, shopping, and sightseeing costs will increase for Korean travelers visiting Japan. #EarningsTurnaround #TechnicalAnalysis #SupplyAndDemandStatus #52WeekHigh #SecuritiesMarketTargetPrice #Besent #ScottBesent #USTreasurySecretary #JapanInterestRateHike #BankOfJapan #UedaZuo #YenStrong #DollarYenExchangeRate #EscapeFromWeakYen #YenCarryTrade #YenCarryUnwinding #USTreasuryYields #US10Y #ExchangeRateStability #KRWDollarExchangeRate #ExportCompetitiveness #KoreanStockMarketVolatility #EndOfAbenomics #GlobalMacro #MonetaryPolicy #ExchangeRateSynchronization #ImportPriceStability #ForeignExchangeMarket #G20FinanceMinistersMeeting #InvestmentStrategy

Posted by 보석
,

NVIDIA (NVDA) FY2027 Q2 (scheduled to be announced after market close on August 26, 2026) Earnings Consensus, Wall Street Target Prices, and Market Downward/Correction Scenarios
​
Here are the NVIDIA (NVDA) FY2027 Q2 (scheduled to be announced after market close on August 26, 2026) earnings consensus, Wall Street target prices, market downward/correction scenarios, and key points.

1. Earnings Forecast (Q2 FY2027 Consensus)

Revenue Estimate: Approx. $91.9 billion to $92 billion (Surge year-over-year, upper end of guidance)

Earnings Per Share (EPS) Estimate: Approx. $2.08 to $2.09

Gross Margin: Expected to be around 75.0%

Key Points to Watch: Shipment speed of Blackwell and next-generation AI chips in the first half, and whether revenue growth in the data center segment will continue.

2. Average Target Price and Investment Opinions

Wall Street Average Target Price: Approximately $297 to $308

Highest Target Price: $350 to $352 (Cantor Fitzgerald, Raymond James, etc.)

Investment Opinions: Most maintain a 'Buy (Strong Buy / Overweight)' rating.

**Potential for Stock Price Decline After Earnings Announcement and Market Perspective**

These are the key causes and technical zones for NVIDIA's stock price decline (correction) scenarios presented by market experts and analysis institutions.

**Slowing of the 'Beat & Raise' Segment (Earnings Surprise Illusion)**

In the past, NVIDIA recorded overwhelming 'earnings surprises' that exceeded market expectations by more than 20%, but in recent quarters, the magnitude of these surprises has narrowed to the 4% to 5% level. As market expectations are set too high, simply meeting earnings levels could trigger a "Sell the News" trend, potentially leading to a short-term correction.

**Possibility of Conservative Next Quarter (Q3) Guidance**

More important than current earnings is the Q3 guidance presented by management.

If nuances regarding supply chain bottlenecks or the pace of AI CAPEX (capital expenditure) by major big tech companies are mentioned, there is a possibility of a sharp sell-off due to concerns over a downward guidance.

**Renewed Doubts on Big Tech AI CAPEX**

If controversies regarding the return on investment (ROI) of major clients such as Microsoft, Meta, and Alphabet resurface, it could lead to a sell-off across tech stocks due to valuation pressures.​

Key support lines on the technical chart during a decline

1st Support Line: $210 ~ $215 range (Upper part of the short-term trend line and moving average)

2nd Support Line (during a full correction): $190 ~ $195 range (Area where the previous major low and the 200-day moving average are formed)

​

A decline in NVIDIA stock is expected.

​

​
=============================================

​
The schedule for NVIDIA (NVDA) Q2 2026 (FY2027 Q2) earnings announcements is as follows.

📌 Earnings Announcement

US Eastern Time (ET): Approx. 4:20 PM on August 26, 2026

US Western Time (PT): Approx. 1:20 PM on August 26, 2026

KST (Korea Standard Time): Approx. 5:20 AM on Thursday, August 27

📌 Earnings Conference Call

US Eastern Time: 5:00 PM on August 26

US Western Time: 2:00 PM

KST: 6:00 AM on August 27

In other words, the earnings announcement will take place after the US market closes today → The earnings are expected to be released around 5:20 AM tomorrow (August 27) KST. According to the official NVIDIA announcement, the conference call is scheduled for 5:00 PM US Eastern Time. **NVIDIA (NVDA) will announce its Q2 2027 fiscal year earnings on Wednesday, August 26, 2026 (U.S. local time).**

### U.S. Time

- **Earnings Announcement (Results Release)**: Approx. **1:20 PM PT** (Pacific Time) / **4:20 PM ET** (Eastern Time)

(After Market Close)

- **Conference Call (Earnings Briefing)**: **2:00 PM PT** / **5:00 PM ET**

(Conducted via webcast, Q&A following prepared remarks)

### Korea Standard Time (KST)

- **Earnings Announcement**: **August 27 (Thu) around 5:20 AM**

- **Conference Call**: **August 27 (Thu) morning 6:00**

The results will be released on investor.nvidia.com, along with CFO comments. As of now (4:42 PM KST, August 26, 2026), it is the day of the announcement.


This is based on the time of NVIDIA's FY2027 Q2 earnings announcement.

US Time (Eastern Standard Time EDT): August 26, 2026 (Wed) between 4:20 PM and 5:00 PM (Press release to be distributed immediately after market close)

Earnings Conference Call: Starts at 5:00 PM (EDT) on the same day

Korea Time (KST): August 27, 2026 (Thu) between 5:20 AM and 6:00 AM

Earnings Conference Call: Starts at 6:00 AM (KST) on the same day


#NVIDIAEarnings #EarningsConsensus #TargetPrice #EarningsSurprise #Guidance #Blackwell #AIsemiconductor #BigTechCAPEX #TechnicalAnalysis #ProfitTaking #StockCorrection #BearishScenario #DataCenterRevenue #EarningsPerShare #RevenueEstimate #USMarket #TechOutlook #SupportLineAnalysis #200DayMovement #IncreasedVolatility #ProfitabilityControversy #SupplyChainBottleback #InvestmentSentiment #StockMarketOutlook #NVIDIAStockPrice #BuyRecommendation #EarningsAnnouncement #GlobalStockMarket #StockMarket #FinancialOutlook

Posted by 보석
,

Micron (MU) - One of the World's Top 3 Memory Semiconductor Manufacturers

Micron (MU) is one of the world's top three memory semiconductor manufacturers and serves as a "global semiconductor bellwether," being the first to announce earnings on the U.S. stock market.

Micron's strong earnings performance acts as a broad positive catalyst for the U.S. stock market as a whole, extending beyond the individual company.

Key Positive Impacts on the U.S. Stock Market

Resolution of AI Bubble Concerns and Securing Justification for Big Tech Investments

Micron's earnings growth is based on a surge in orders for HBM (High Bandwidth Memory) and server DRAM from Big Tech (big-scaler) companies.

This demonstrates that the AI ​​capital expenditures (CapEx) being pursued by Nvidia, Microsoft, Google, Amazon, and others are leading to actual demand rather than a short-term bubble.

Semiconductor and Big Tech Sectors (SOXX, QQQ) Rise Together

Micron's earnings surprise and positive guidance are the most definitive catalysts driving up the Philadelphia Semiconductor Index (SOXX).

This triggers improved investor sentiment across the AI ​​value chain, ranging from design firms like Nvidia, AMD, and Broadcom to equipment stocks like AMAT and Lam Research, thereby driving the Nasdaq Composite Index upward.


Confirmation of a Long-term Supercycle in the Memory Semiconductor Market

Rising prices for DRAM and NAND flash, coupled with the persistence of supply-demand imbalances, dramatically enhance profit visibility for the memory industry.

Beyond a simple cyclical boom, the risk of earnings volatility is reduced through long-term contract (SCA) structures, serving as a catalyst for the re-rating of valuations (multiples) across the entire semiconductor sector. Increased Inflow of Foreign and Passive Funds into the Stock Market

Because technology stocks account for a high proportion of major U.S. indices (S&P 500, Nasdaq 100), positive earnings news from Micron creates a virtuous cycle of supply and demand, leading to a strong inflow of index funds and passive funds into the entire stock market.

Posted by 보석
,

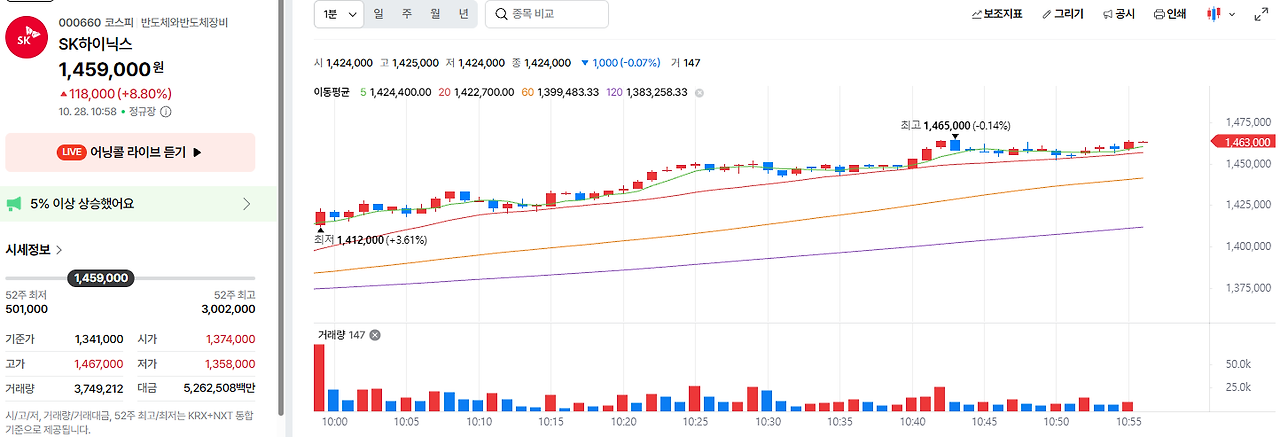
August 10 - SK Hynix - Expected to Hit Upper Limit!!! It's cheap~ Buy quickly~~ Don't be late~

Leveraging its record-breaking exclusive supply of HBM3E/HBM4 and earnings growth, SK Hynix has abruptly moved its announcement of additional shareholder returns—originally scheduled for the end of the year—to the third quarter (September). Expectations in the market regarding a 40 trillion won share buyback and cancellation, along with massive shareholder returns totaling around 100 trillion won, could serve as the key triggers causing an explosion in supply and demand.

**Scenario for Hitting Upper Limit Next Monday**

**Timeline for Global Tech Stock Rebound and Weekend Big News (Sat-Sun)**

**Nvidia and Philadelphia Semiconductor Index Surge: Reaffirmation of Explosive Demand for AI Chips and Sharp Rebound in Global Stock Markets Over the Weekend** Flood of reports from foreign media and brokerage firms: Reports plastered with headlines such as "SK Hynix's 100 trillion won return plan, including the cancellation of 40 trillion won in treasury shares, becoming visible within Q3," and "Target price raised to over 3 million won."

**Pre-market simultaneous bidding (08:30 ~ 09:00)**

**Strong buy orders from foreign and institutional investors accumulate: Strong buy orders gathered before the market opened, driven by the positive news of an early announcement regarding shareholder returns and expectations of a massive inflow of FCF (Free Cash Flow).

**Opening with a gap-up:** The stock gapped up by over +15% from the opening price, attempting to break through the previous high in a single stroke.

**Intraday supply and demand explosion and settlement at the upper limit (09:00 ~ 15:30)**

**Foreign and institutional short covering and short squeeze: Simultaneous inflow of emergency repayment volumes from existing short positions and passive funds from institutions.

**Consolidation of buy orders at the upper limit:** Coinciding with the breaking news confirming the exclusive HBM4 supply contract, buy orders of tens of millions of shares accumulated at the +30% upper limit price as the afternoon session opened, effectively closing the day.

**3. Technical Analysis and Supply & Demand Status**

**Transition in Supply & Demand Structure:** The early disclosure of the Q3 shareholder return plan has created an environment conducive to a strong inflow of passive funds from foreign and institutional investors.

**Key Chart Points:** If the shareholder return momentum aligns with the significant lead in HBM performance, it is highly likely that a strong long bullish candle will form, resuming an upward rally toward the previous high (2,987,000 KRW). #SKHynix #ShareholderReturn #HBM4 #TreasuryStockCancellation #DividendIncrease #PrayingForLimitUp #LeadingSemiconductorStock #FCF100TrillionWon #ForeignInvestorBuyingStorm #InstitutionalNetBuying #AIMemory #NVIDIAPartner #NextGenHBM #EarningsExplosion #TargetPriceUpgrade #MarketLeadingStock #DrivingKOSPI #RecordBreakingEarnings #StockPriceRise #NewHigh #EnhancingShareholderValue #SeptemberShareholderReturn #TopPositiveNews #SupplyAndDemandSwing #ShortSqueeze #TechnicalAnalysis #ChartBreakout #SemiconductorBoom #KukjeonStock #StockJackpot

Posted by 보석
,

Iran-Oman Agreement (20% toll on ships passing through Hormuz) - If Trump doesn't agree, the stock market will probably go short... T_T.

**Does the stock market fall if Trump doesn't approve it?**

Here, "approval" likely refers to the Iran-Oman agreement regarding tolls. Trump's stance has been very erratic recently.

Trump declared that the U.S. would collect a 20% toll on ships passing through Hormuz, but reversed his position within a day—to the point where even his aides were shocked. Following persuasion from Gulf states, he withdrew the plan to impose tolls and announced that he would replace it with attracting investment to the U.S. instead.

**Secretary of State Rubio stated that "Hormuz is an international waterway, and no country can impose tolls," and the International Maritime Organization (IMO) also opposed the imposition of tolls, citing a lack of legal basis. Against this backdrop, the impact of "Trump's approval" on the stock market is as follows:

If Trump opposes the Iran-Oman transit agreement rather than approving it → there is a risk that the reopening of the strait will be delayed or canceled → uncertainty regarding crude oil supply will persist → upward pressure on oil prices → renewed concerns about inflation → this could become a burden on the stock market (especially growth stocks sensitive to interest rates).

However, since Trump's statements have been reversed several times over the past few days, it is difficult to conclude that the stock market will trend downward based solely on this, even if there is short-term volatility. Rather, the market has already largely factored in this geopolitical risk, and it is highly likely that it will be fully reflected in the stock market only when more concrete negative factors emerge, such as a surge in oil prices or a recurrence of physical clashes.

Summary: "Restrictions on hostile ships" is closer to a reaffirmation or extension of existing policy than new news, and the impact on oil prices and the stock market depends on whether the Iran-Oman reopening agreement is actually concluded and what final stance Trump takes regarding the transit issue. As this is an ongoing matter, the stance could change within a day or two; therefore, I advise you to approach investment decisions based on hearsay rather than confirmed news with caution. Since I am not a financial advisor, it is best to check both the latest breaking news and expert opinions before making an actual investment decision.

Posted by 보석
,

NVIDIA Reduces HBM and Increases GPUs – Is It a Short? What Is It?

Looking at recent articles, the trend of "NVIDIA reducing HBM and increasing GPUs" is intertwined with several different contexts.

1. Re-evaluation of Rubin Ultra HBM Specifications
As the supply shortages of DRAM and HBM are expected to continue into next year, AI chip manufacturers, including NVIDIA, are considering lowering the HBM specifications for their next-generation products. According to TrendForce, NVIDIA has been evaluating the memory configuration of the Rubin Ultra since the third quarter by expanding it beyond the existing 12-layer HBM4E to include various specifications such as 8-layer HBM4E, 12-layer HBM4, and 8-layer HBM4; however, the final specifications remain unconfirmed. This is analyzed to be due to the fact that memory manufacturers' HBM production capacity is limited by next year's DRAM supply shortage, and uncertainty remains regarding the certification schedule and yield of 12-layer HBM4E. 2. Allocating Memory to AI Chips Instead of Gaming GPUs
According to The Information, Nvidia is considering abandoning the launch of new gaming GPUs in 2026 due to memory supply constraints. In other words, this is closer to meaning that limited HBM resources will be allocated to highly profitable AI accelerators and resources for gaming will be reduced, rather than simply "reducing HBM."

3. The Actual Context of the Article Claiming "HBM to be Reduced by 30%"
The article states that client companies (Big Tech), facing skyrocketing HBM prices and supply shortages, are accelerating the development of compression technologies to reduce memory usage itself. This indicates that Nvidia is not voluntarily reducing memory, but rather is a move to adjust specifications or work around the issue via software out of necessity due to the supply shortage.

Regarding the Hypothesis that "If Memory is Reduced, Investments and the Stock Market Will Fall"

Current data actually points in the opposite direction. TrendForce projected that the share of HBM demand accounted for by NVIDIA AI accelerators would drop from 66% last year to 58% this year; however, this does not mean that NVIDIA is reducing its HBM purchases, but rather that demand is being diversified as other sources of demand, such as Google’s TPUs, increase. TrendForce characterized this memory upcycle as a "structural supercycle" continuing from 2026 to 2028, and predicted that supply bottlenecks would not be easily resolved despite increased investment as existing DRAM and NAND production lines transition to HBM4 and HBM4E production.

TrendForce estimates the global memory market size at $889.3 billion this year and forecasts it will surpass $1.28 trillion by 2027 (with a growth rate of approximately 44% in 2027).

SK Hynix stated that all of its HBM products were sold by 2026, and Samsung Electronics has also announced that its major customers have secured future release volumes. In other words, the fact that "Nvidia is lowering HBM specifications" is a phenomenon occurring due to supply shortages or yield issues, rather than a decrease in demand; in fact, this is often interpreted as a signal demonstrating just how severe the HBM scarcity is. However, there are also warnings that if the completion of Big Tech's memory reduction (compression) technology coincides with the supply expansion around 2027—when new factory expansions by Micron and Korean companies flood the market—downward pressure on market valuations could increase. Therefore, this is a risk factor that warrants close monitoring.

In summary: News so far suggests that specifications are being adjusted in a situation where supply cannot keep up with demand, rather than a scenario of "reduced memory investment → semiconductor stock market decline." However, there is also a cautious view that a phase of oversupply and price adjustments could occur once new capacity expansions begin in earnest after 2027 and memory reduction technology spreads simultaneously. Therefore, it would be advisable to consider both scenarios together.

** This content is a summary of information for investment reference only. I am not a financial advisor, so I recommend that you conduct further verification and consult with a professional before making actual investment decisions.

Posted by 보석
,